What is the scope and industry significance of the Metal Stamping Market?
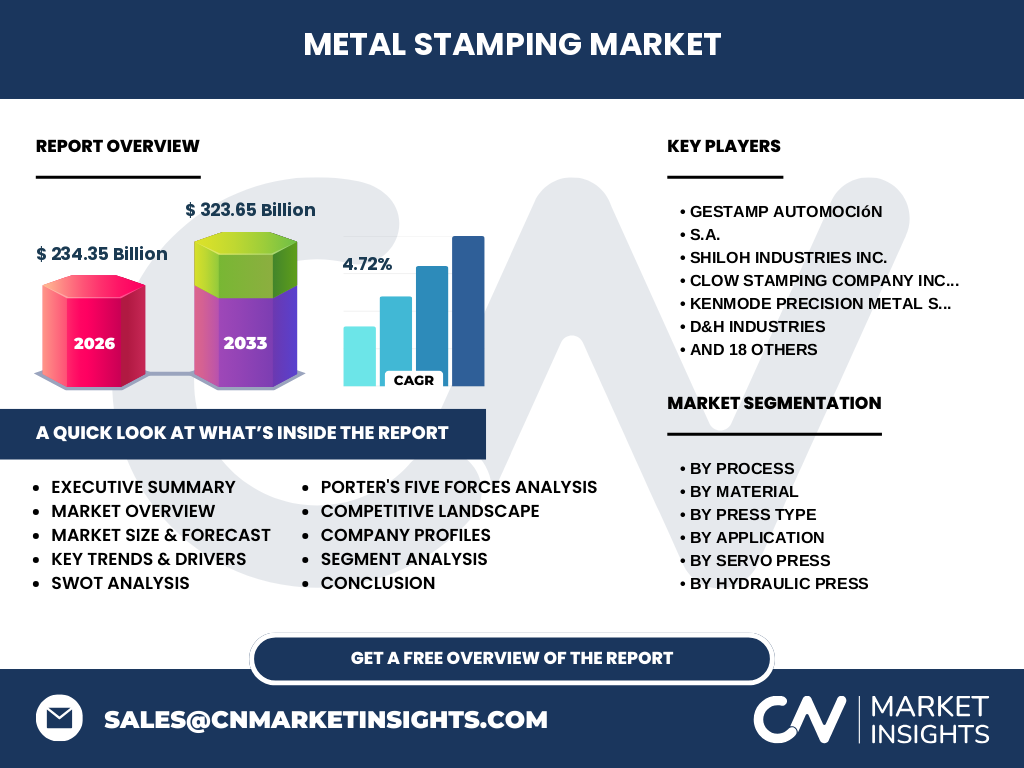
Our analysis indicates that the Metal Stamping Market size stands at $234.35 Billion in 2026, serving as a critical foundational pillar for high-volume component manufacturing across automotive and electronics sectors. Utilizing raw materials like advanced high-strength steel, aluminum, and copper, the industry converts flat sheet metal into precision components through specialized press technologies.
Key market drivers, restraints, challenges, and opportunities shaping the Metal Stamping Market
Growth is propelled by lightweighting mandates in electric vehicles and consumer electronics. However, volatile raw material pricing for aluminum and copper creates margin compression. Opportunities lie in integrating servo press systems to enhance energy efficiency and reduce scrap rates during complex deep drawing and blanking procedures.
Emerging trends and growth patterns in the Metal Stamping Market
The industry is experiencing a rapid shift toward advanced automation and IoT-enabled die monitoring. Manufacturers are increasingly adopting servo-electric and hybrid servo presses to achieve superior stroke control. This technological evolution directly benefits pioneers like Kenmode Precision Metal Stamping and Interplex Holdings Pte. Ltd. in producing ultra-miniaturized components.
COVID-19 impact analysis on the Metal Stamping Market and recovery trajectory
The pandemic caused severe supply chain disruptions across automotive hubs in North America and Europe, stalling tier-1 suppliers such as Gestamp Automoción and Shiloh Industries Inc. The subsequent recovery trajectory highlights a strong rebound driven by pent-up demand and localized reshoring of stamping operations closer to OEM assembly plants.
Competitive landscape of the Metal Stamping Market
The market features a fragmented yet highly competitive landscape characterized by aggressive capacity expansions and strategic tier-1 consolidations. Major players like Martinrea International Inc., Linamar Corporation, and Tower International leverage global manufacturing footprints to secure long-term automotive and industrial supply contracts.
Executive summary of key findings for the Metal Stamping Market
Our comprehensive research projects the Metal Stamping Market to reach $323.65 Billion by 2033, expanding at a robust CAGR of 4.72% from 2027. Stakeholders must prioritize multi-material handling capabilities and energy-efficient press investments to capture high-margin opportunities in aerospace, medical, and electric vehicle applications.
Metal Stamping Market forecast from 2027 to 2033
Driven by rising automation adoption and stringent safety regulations enforced by bodies like OSHA and ISO, the sector is set for steady upward momentum. The trajectory from 2027 to 2033 will see accelerated investments in servo press infrastructure, unlocking higher throughput for complex geometries in industrial machinery and telecommunications.
Segmentation analysis of the Metal Stamping Market
Segmentation is categorized by Process (Blanking, Embossing, Bending, Coining, Deep Drawing, Flanging), Material (Steel, Aluminum, Copper), Press Type (Mechanical, Hydraulic, Servo), and Application. Automotive applications dominate consumption, while servo press sub-segments like Direct Drive and Servo-Electric dictate high-precision manufacturing trends.
Regional market analysis and geographic performance
Geographic performance is led by North America and Europe, supported by rigorous automotive manufacturing standards. Meanwhile, the Asia-Pacific region demonstrates the fastest expansion due to surging consumer electronics production and rapidly scaling industrial machinery sectors in localized manufacturing clusters near major maritime trade hubs.
In-depth regional review of the Metal Stamping Market
North America benefits from established supply chains anchored by key stamping specialists like D&H Industries, Inc. and Harvey Vogel Manufacturing Co. Conversely, European markets face stricter environmental directives, pushing localized players like Sertec Group Ltd toward sustainable aluminum processing and energy-efficient hydraulic press operations.
Strategic positioning of leading companies in the Metal Stamping Market
Industry leaders like Gestamp North America, Trans-Matic Manufacturing Company, and Manor Tool & Manufacturing Company deploy distinct differentiation strategies. While Gestamp focuses on massive structural automotive assemblies, Trans-Matic excels in high-precision deep drawing for medical and aerospace end-users.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to the commodity nature of steel and aluminum coils. However, buyer power is high among major automotive OEMs who demand rigorous quality certifications, press capability audits, and aggressive cost-down models from independent stamping houses.
SWOT analysis of the Metal Stamping Market
Strengths include unmatched component durability and cost-efficiency at high volumes. Weaknesses involve high initial capital expenditure for servo presses. Opportunities reside in lightweight EV architecture integration, while threats stem from alternative composite manufacturing technologies challenging traditional metal components.
Value chain analysis from raw materials to end-users
The value chain initiates with primary metal producers supplying coils of steel, aluminum, and copper. Tier-1 and tier-2 stampers utilize mechanical, hydraulic, or servo presses to form parts, followed by secondary finishing, ultimately supplying original equipment manufacturers in automotive, aerospace, and electronics.
Investment insights and strategic recommendations
Investors should target acquisitions of regional facilities equipped with advanced servo press technology to capitalize on high-margin medical and aerospace applications. Companies possessing in-house tool and die design capabilities offer superior valuation multiples in the current market environment.
Conclusion and key takeaways for industry stakeholders
The Metal Stamping Market trajectory through 2033 underscores the necessity of technological modernization. Firms that successfully transition from legacy mechanical presses to agile servo-electric systems will best navigate raw material volatility and capture surging demand across electrification domains.
Research methodology used for the Metal Stamping Market analysis
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with executives at firms like Clow Stamping Company Inc. and Goshen Stamping Company, and secondary macroeconomic indicators regarding global automotive production volumes and industrial output indexes.
Scope of the report and coverage parameters
This report covers global revenue estimations, volume metrics, and competitive benchmarking for the Metal Stamping Market from 2026 through 2033. Limitations include localized tariff fluctuations and sudden raw material supply shocks that may impact short-term regional production outputs.
Recent developments in the Metal Stamping Market
Recent strategic moves feature major automotive stampers investing heavily in multi-axis servo transfer presses to reduce setup times. Collaborations between technology innovators and regional players such as S-MEX S.A. de CV and AAPICO Hitech Public Company Limited highlight an industry-wide push toward automated smart-factory integration.